How Much Cash Can You Safely Take as an Owner Draw?
11/15/2026
By Talia. E
A profitable month can still leave a business short on spendable cash. A profit and loss statement measures revenue and expenses for a period, while cash reporting shows when money actually entered or left the business. The Financial Accounting Standards Board notes that earnings are not the same as cash flow from operations, which is why a cash-flow view is useful alongside profit. FASB Conceptual Framework, Chapter 7
A more useful question than “What did we make?” is “What cash will be available after the commitments already in motion?” That question helps an owner decide whether a draw is sensible this week without confusing unpaid invoices, upcoming bills, loan principal, or a needed cash cushion with profit.
Profit is a scorecard; cash is what can pay Friday’s bills
Profit generally starts with revenue minus expenses. But an invoice can count toward revenue before the customer pays, and a bill can be recorded before cash leaves the account. The SBA cautions that credit sales become accounts receivable, so sales shown on a profit and loss statement are not necessarily cash in the bank. SBA: 5 Classic Fails in Budgets and Forecasts
Cash can also be used by items that do not reduce current-period profit in the same way: buying equipment, paying down loan principal, building inventory, repaying an owner loan, or taking money out for personal use. A statement of cash flows separates cash activity into operating, investing, and financing categories so readers can see the source and use of cash. FASB Conceptual Framework, Chapter 7
- Profit can include invoices that have not been collected.
- Bank cash can be reduced by bills, debt payments, equipment purchases, and owner withdrawals.
- A positive bank balance is not automatically available cash if payroll, taxes, or vendor commitments are due soon.
Build a two-week cash view before taking a draw
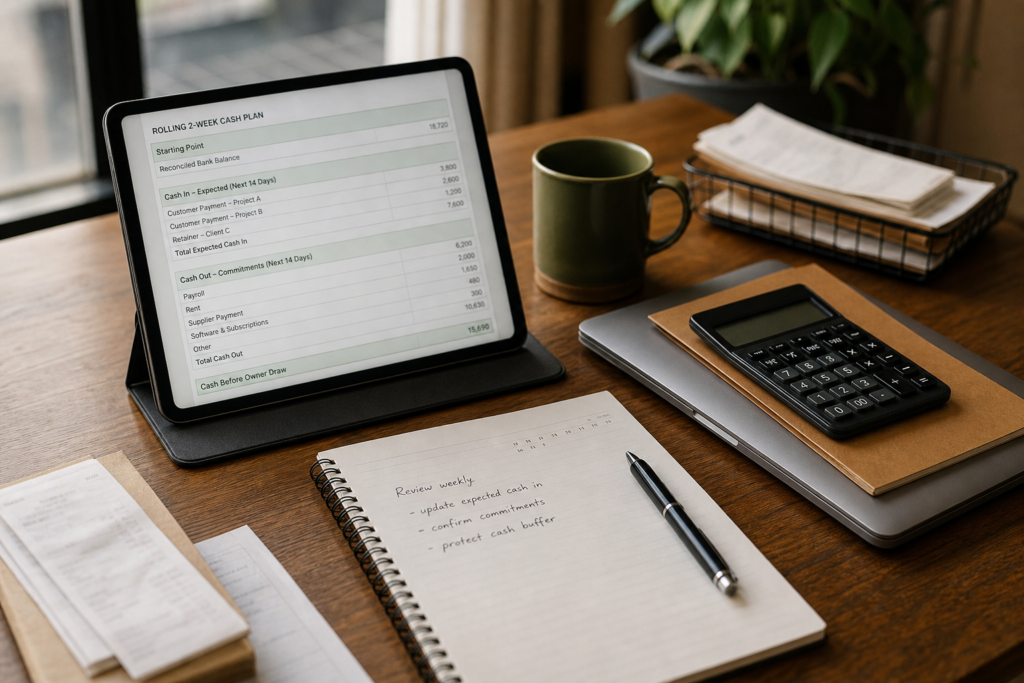
Use a short rolling plan, updated at least weekly. Start with the reconciled bank balance, then add only cash you reasonably expect to receive during the next two weeks. Do not use the full accounts-receivable balance as though every invoice will arrive on time.
Next, subtract the cash commitments that must be covered in that same period. The remainder is not a promise to spend; it is the amount left before you decide how much protection the business needs.
- Starting cash: use the reconciled bank balance, not a stale bank-feed total.
- Expected collections: include customer payments by their likely receipt date, not invoice date.
- Required outflows: payroll, payroll taxes, rent, supplier bills, card payments, debt principal and interest, and committed job costs.
- Reserves: include a tax reserve if applicable and a minimum operating buffer.
- Potential owner draw: consider only what remains after the items above.
Work a simple owner-draw example
Suppose a service business has $22,000 in reconciled cash. During the next two weeks, it expects to collect $8,000 from customers. It also expects $7,000 of payroll, $5,000 of supplier and operating bills, $1,500 of debt payments, and $2,000 moved into its tax reserve. The owner wants to preserve a $7,000 operating buffer.
The calculation is $22,000 + $8,000 − $7,000 − $5,000 − $1,500 − $2,000 − $7,000 = $7,500. In this example, $7,500 is the maximum cash remaining under the plan, not an amount the owner must withdraw. If the expected collection is uncertain, late, or already overdue, reduce the draw or wait until the payment clears.
This is also why an unpaid $10,000 invoice should not be treated like spendable cash. Keep it visible in accounts receivable, note its expected collection date, and follow up before it becomes the reason payroll or a supplier bill is delayed.
Keep owner money separate from operating costs
For a sole proprietor, the IRS advises using the business account for business purposes and writing checks payable to yourself when making withdrawals for personal use. It also recommends reconciling the checking account each month so the bank statement, checkbook, and books agree. IRS Publication 583: Starting a Business and Keeping Records
In your bookkeeping, identify the withdrawal clearly as an owner transaction rather than hiding it in rent, supplies, subcontractors, or another operating expense. That keeps job margins and operating profit more useful. It also makes the cash plan easier to read: the business generated cash, then an owner chose to remove some of it.
The correct legal and tax classification of money paid to an owner can vary by entity type and tax elections. A sole proprietor, partnership owner, S corporation shareholder, and corporate owner should not assume the same treatment. Use this cash-planning process to make the operating decision, and confirm the bookkeeping and tax treatment for your business structure with a qualified tax professional.
- Record the date, amount, and purpose of each owner withdrawal.
- Keep personal spending out of business expense categories.
- Reconcile bank and credit-card accounts before relying on cash reports.
- Review overdue customer invoices and unpaid vendor bills with the cash plan, not just at year-end.
Use the same framework in your industry
The cash categories stay consistent, but the pressure points differ by business model. The SBA recommends using monthly projections for the first year of a business plan; established businesses can also use that discipline in a near-term weekly view when cash timing is tight. SBA: Plan Your Business
Set the review date, identify the next cash bottleneck, and update the plan after material changes such as a delayed customer payment, a purchase order, a large repair, or a payroll change.
- Trades and remodelers: list deposits received, materials ordered but not yet paid, subcontractor commitments, progress-billing dates, and retainage separately.
- Retail, ecommerce, and restaurants: plan around processor payout timing, inventory orders, refunds, sales-tax obligations, and payroll.
- Professional services and agencies: track each client invoice by expected payment date and compare it with upcoming payroll and contractor commitments.
- Property services and landlords: separate security deposits, rent collections, repairs, debt service, and property-specific reserves.
- Traders and side hustles: keep business activity separate from personal transfers and do not treat brokerage or platform balances as operating cash until their availability and purpose are clear.
Frequently asked questions
If my P&L shows a profit, why is my bank balance low?
Common reasons include unpaid customer invoices, bills paid before revenue is collected, inventory or equipment purchases, debt-principal payments, tax transfers, and owner withdrawals. Profit measures a period’s results; the bank balance reflects cash timing and other uses of cash.
Should I count unpaid invoices when deciding on an owner draw?
Track them, but do not treat them as cash until you have a realistic collection date. For a conservative short-term plan, include only amounts you reasonably expect to receive before the bills you need to pay.
How often should I update a cash plan?
Weekly is a practical starting point for many small businesses, especially when payroll, supplier payments, or customer collections can change quickly. Update it sooner after a large unexpected bill or a delayed payment.
Is an owner draw the same as payroll?
Not necessarily. The correct owner-payment treatment depends on the business’s legal structure and tax elections. Keep the cash decision separate from the classification question, and ask a qualified tax professional how payments to owners should be recorded for your entity.
Sources and further reading
This article provides general educational information and is not tax, legal, accounting, or investment advice. Rules and individual circumstances can change; consult an appropriately qualified professional for advice about your situation.