Quoted vs. Actual Job Costs: A Monthly Review
11/18/2026
By Talia. E
A job can be fully paid, look busy, and still produce a disappointing margin. The usual reason is not one dramatic mistake. It is a collection of differences between the quote and what actually happened: extra labor time, an unassigned receipt, a subcontractor overage, a return visit, or work completed outside the original scope.
The practical answer is a monthly quoted-versus-actual review. It does not require perfect cost accounting or elaborate software. It requires a repeatable job record, timely source documents, and a short process for turning variances into better future quotes. The IRS notes that business records should be supported by documents such as invoices, receipts, paid bills, sales slips, and account records, and that recording expenses when they occur makes the system more effective. IRS Publication 583: Starting a Business and Keeping Records
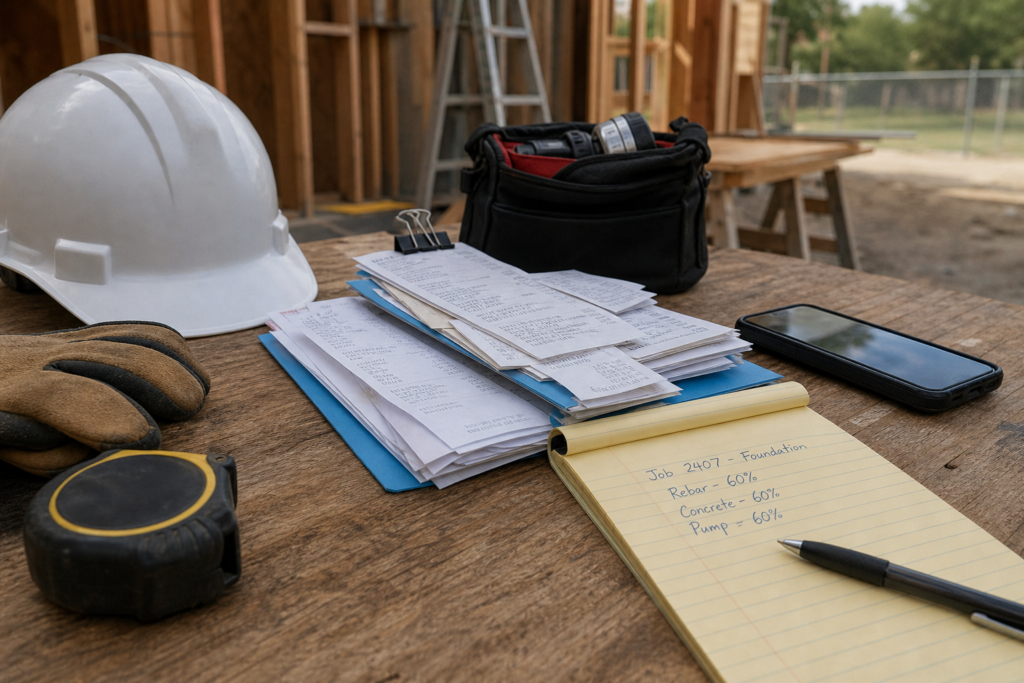
Start with one job-cost card for every quoted job
Create a job-cost card when the quote is approved, before the first hour is worked or purchase is made. Give the job a clear name or number, record the quoted revenue, and split the estimated cost into the same categories you will use for actual costs.
For most service and project businesses, four direct-cost buckets are enough to begin: labor, materials, subcontractors, and other job-specific costs. Other job-specific costs may include permits, equipment rentals, disposal fees, mileage reimbursements, freight, or a specialized software purchase used only for that project. Keep recurring business-wide costs, such as office rent and general advertising, separate from the direct job-cost comparison unless you have adopted a consistent internal allocation method.
- Job name or job number
- Customer and quoted revenue
- Estimated labor hours and estimated labor cost
- Estimated materials cost
- Estimated subcontractor cost
- Estimated other job-specific cost
- Approved change orders, with both added revenue and added expected cost
Make actual costs easy to capture before month-end
The quality of the review depends on the quality of the underlying records. Ask employees, owners, and project leads to include the job number when submitting time, receipts, purchase invoices, and subcontractor bills. If one supplier bill covers multiple jobs, split it by the portion that belongs to each job rather than assigning the entire bill to the most recent project.
A bank or card transaction confirms that money moved, but it may not show the business purpose or the job served. Keep the invoice, receipt, or other supporting record with a brief job note. The IRS says proof of payment alone does not establish a deduction; supporting documents help show that the cost was incurred and what it was for. IRS Publication 583: Supporting Documents and Expenses
- Enter labor hours by job at least weekly; daily is better for active crews.
- Attach or store the supplier receipt with the job number and cost category.
- Record subcontractor commitments and bills against the job.
- Add a change-order entry when scope changes, rather than burying extra labor in the original quote.
- Review uncategorized card and bank transactions before closing the month.
Run the monthly quote-to-actual comparison
At month-end, review every open job and every job completed during the month. Compare estimated and actual amounts category by category, not only as one total. A total can look acceptable while a serious labor overrun is hidden by lower-than-expected material spending.
For open work, use actual cost to date plus known remaining commitments to make a simple forecast. For example, if a $6,000 job was quoted with $2,000 of labor, $1,800 of materials, $600 of subcontractors, and $200 of other direct costs, the estimated direct cost was $4,600. If actual direct costs are now $5,150, the direct-cost variance is $550 unfavorable. The next question is whether additional work or costs remain before the job is complete.
For closed work, calculate the final direct-cost variance: actual direct cost minus quoted direct cost. Then identify the cause in plain language: extra site visit, missed supplier price increase, incorrect labor assumption, customer-requested change not billed, or a one-time issue unlikely to recur.
- Quoted revenue versus invoiced revenue
- Quoted labor hours versus actual labor hours
- Quoted direct cost versus actual direct cost
- Actual direct-cost variance by category
- Unbilled or underbilled approved changes
- Estimated remaining cost for open jobs
Separate a job-cost warning from a final profitability decision
A direct job-cost comparison is a useful operating signal, but it is not automatically the same as final company profit. Your business also has indirect costs that support many jobs, such as management time, rent, insurance, dispatch, software, and general vehicle costs. Decide on a consistent internal approach for reviewing those costs instead of changing the approach from job to job.
For a simple first stage, use quoted-versus-actual direct costs to find execution and estimating problems. Then review your monthly income statement to see whether gross-margin performance is sufficient to cover indirect expenses and leave an operating profit. The SBA advises business owners to maintain bookkeeping and understand money coming in and going out to support a sustainable balance between profit and loss. SBA: Manage Your Business
Do not let the tax treatment of an item decide whether it belongs in your internal job-cost report. Your job-cost card is a management tool. Your books and tax return still need records that accurately support the underlying transaction.
- Use direct costs to diagnose a particular job.
- Use the monthly income statement to evaluate the business as a whole.
- Apply any overhead allocation consistently for comparable jobs.
- Keep owner draws separate from job expenses; record actual job work consistently if you want to assess the economics of owner-performed work.
Turn each variance into a better next quote
A monthly review becomes valuable when it changes the next estimate. Choose the two or three largest recurring causes of unfavorable variance and update the estimating assumptions. If labor is consistently over budget, revise production assumptions or include the full time required for travel, setup, cleanup, client communication, and return visits. If materials run over, improve takeoffs, refresh supplier pricing, or require approval before substitutions.
Keep a short variance note for each completed job. Over time, these notes form a practical pricing library: what similar work was quoted at, what it actually consumed, and what changed. A professional accounting source describes cost-accounting work as analyzing production cost records for completeness and comparing budgeted costs with actual costs in periodic reports. The same basic discipline can help a smaller service business, even with a spreadsheet. AICPA & CIMA: How to Hire a Cost Accountant
- Review the largest favorable and unfavorable variances monthly.
- Label the cause: estimating, purchasing, labor efficiency, scope, billing, or one-time event.
- Update the quote template only when a pattern appears across comparable jobs.
- Discuss active-job overruns early, while there may still be time to manage scope or costs.
- Keep completed job cards for future estimates and month-end review.
Frequently asked questions
How often should I compare quoted and actual job costs?
Review active jobs at least monthly, and more often for large, fast-moving, or high-risk jobs. Close out the comparison after the final costs and final invoice are recorded. A weekly labor-and-material check can be helpful when a job has a short timeline or a narrow expected margin.
What if I do not have job-costing software?
Start with a spreadsheet or a consistent report from your bookkeeping system. Use one row per job and columns for quoted revenue, estimated cost categories, actual cost categories, invoiced revenue, and variance notes. Consistent data entry matters more than sophisticated software with incomplete records.
Should overhead be assigned to every job?
It can be useful for internal pricing and profitability analysis, but first make direct costs reliable. If you allocate overhead, use one clear method consistently across similar jobs, such as a percentage of revenue or labor hours. Do not mix methods from job to job just to make a result look better.
What is the most common reason a job looks profitable but is not?
Missing or late cost information is a common problem: unrecorded time, receipts that are not assigned to the job, supplier bills that arrive after closeout, and extra work that was performed but not billed. A job-cost card and a monthly review are designed to surface those gaps.
Sources and further reading
This article provides general educational information and is not tax, legal, accounting, or investment advice. Rules and individual circumstances can change; consult an appropriately qualified professional for advice about your situation.